Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
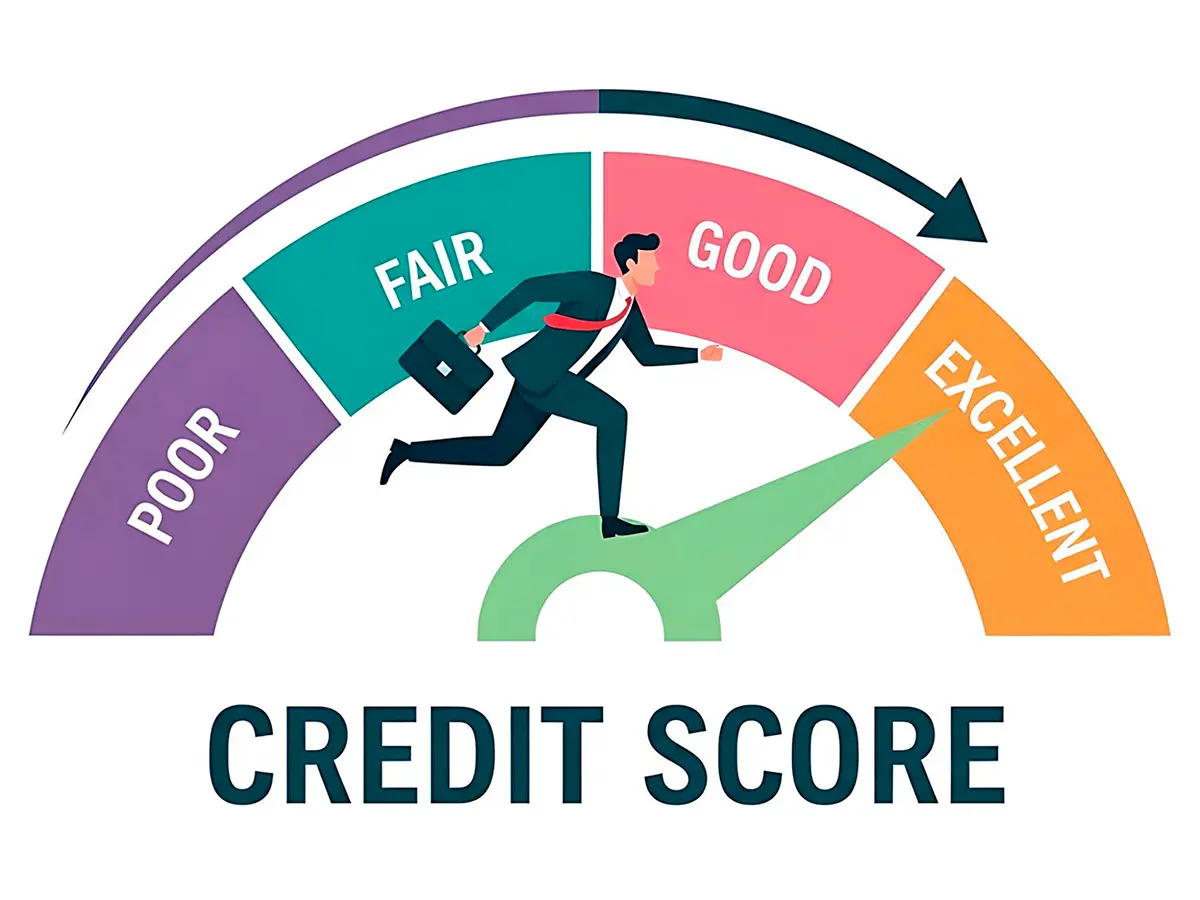
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
improve your credit score with performance-driven habits
I treat my credit like a system to be tuned. I can't promise overnight jumps, but consistent inputs usually deliver compounding results. The key is evaluating what truly moves the score and executing with timing, precision, and a little patience.
Metrics that actually change performance
- Payment history: Every on-time mark is a compounding signal. One late can echo for years.
- Utilization: I aim for overall and per-card utilization under 9%, ideally 1 - 3% reporting on a single card.
- Age of credit: Older accounts stabilize the profile. Closing old cards can backfire.
- Account mix: A healthy blend of revolving and installment accounts can add polish.
- Inquiries and new accounts: Small dings, but clustered openings can drag.
- Derogatories: Collections, charge-offs, and late payments weigh heavily; addressing them yields outsized gains.
My weekly ritual: review reports, check utilization, and verify statement cut dates. It's mundane - and effective.
Tactical moves and sequencing
- Pull all three reports and compare line by line. I flag inaccurate limits, dates, or statuses; they distort utilization and age.
- Autopay with guardrails: a floor (minimum due) plus a calendar reminder to push a manual payment to hit target utilization before statement cut.
- Time the balance: I let one card report a tiny balance (AZEO) while the others report zero. Then I pay that sliver right after it posts.
- Right-size limits: If utilization is stubborn, I request a soft-pull limit increase on strong accounts. If granted, I avoid adding new spend.
- Derogatory triage: Validate every negative. For inaccuracies, dispute with documentation. For accurate lates, a polite goodwill request sometimes works. For collections, a careful pay-for-delete can help - verify policies in writing.
- Build depth, not noise: A secured card or a small installment builder can thicken a thin file. I space new accounts roughly 3 - 6 months apart.
- Authorized user (selective): I only join accounts with long age, perfect history, and low utilization - and I confirm the issuer reports AU data.
A quick real-world moment
Last month, at 9 p.m., I opened my banking app after a limit increase offer. I ran a payoff simulation, realized the added limit would drop utilization from 11% to 5%, accepted it, then paid three days before the statement cut so only one card showed a 2% balance. The score nudged up the next update - modest, but measurable.
Measure progress, avoid friction
- Calendar the cut dates: Statement timing beats guesswork.
- Protect age: I keep old $0-fee cards open and active with tiny recurring charges.
- Rate-shop smart: Mortgage/auto pulls within a short window typically count as one; I batch them.
- Don't chase points at the expense of utilization: Rewards evaporate if a balance reports high.
- Freeze for control: A credit freeze reduces surprise inquiries.
- Watch refunds and credits: Mid-cycle credits can still leave a high reported balance if new charges post before the cut.
Results vary a bit across bureaus, but I usually see small changes within 30 - 60 days and stronger traction over 6 - 12 months of clean data.
Evaluate trade-offs
Sometimes I accept a short-term dip - like a new account - in exchange for lower long-term utilization and better limit-to-income optics. Before a mortgage, I pause new credit, lock in AZEO, and document every dispute and resolution.
Keep the loop tight: evaluate, act, verify, adjust. With steady inputs and mindful timing, your profile's performance generally follows.
Low credit scores can be a serious stumbling block for many hopeful homebuyers. But with patience and hard work, it's possible to improve your credit scores.
Many credit-scoring models consider the number and type of credit accounts you have. A mix of installment loans and credit cards may improve your score. However ...
How to build credit fast - 1. Pay credit card balances strategically - 2. Ask for higher credit limits - 3. Become an authorized user - 4. Pay bills ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.